UM + UIM required
North Carolina coverage menu: liability, UM and UIM on every policy
North Carolina rewrote its minimums on July 1, 2025. Liability limits went up, underinsured motorist coverage became part of every policy, and UIM stopped shrinking by what the at-fault driver's insurer pays.
By CoverOath Editorial Team Updated 7 min read
The promise, in short
For policies issued or renewed on or after July 1, 2025, North Carolina requires 50/100/50 liability, up from 30/60/25. Every policy must also carry uninsured motorist coverage for injuries and property damage and underinsured motorist coverage, at your liability limits unless you choose other limits no lower than the minimums. UIM is no longer reduced by the at-fault driver's liability payment. There is no PIP requirement. The North Carolina Department of Insurance takes consumer calls at 855-408-1212.
- Minimum liability
- 50/100/50
- PIP
- No PIP; MedPay optional
- UM/UIM
- Both required
North Carolina coverage menu
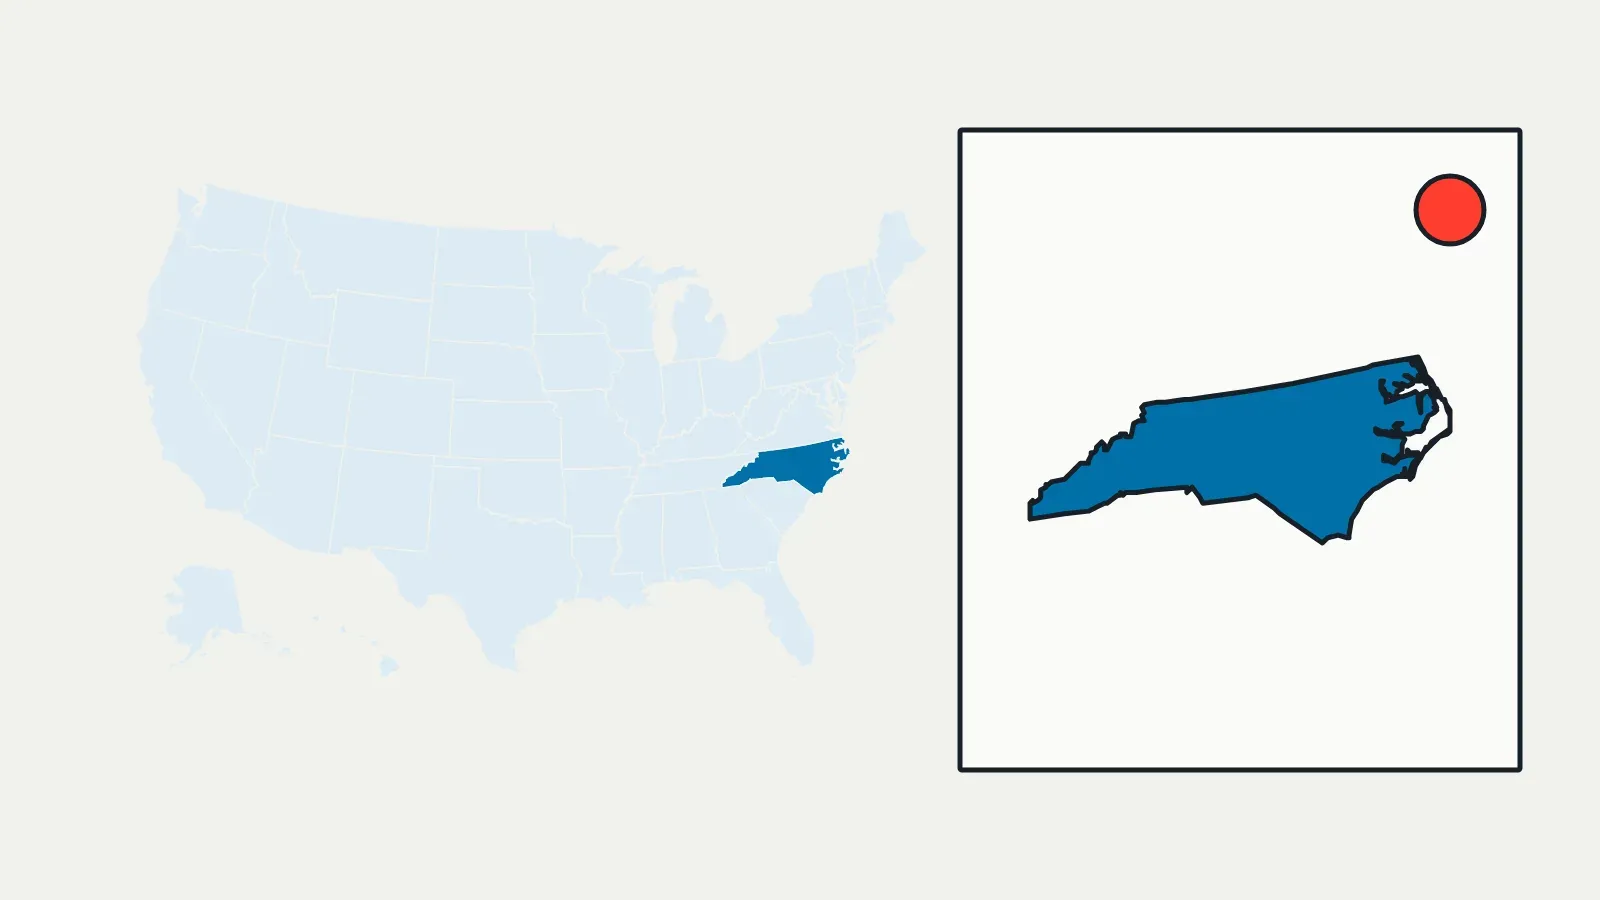
What a North Carolina policy must carry
The North Carolina Department of Insurance lists the July 1, 2025 changes under Session Law 2023-133, as amended by Session Law 2024-29. They apply to new and renewed policies from that date. If your policy was at the old minimums, it moved to the new ones at renewal.
| Coverage | Before July 1, 2025 | From July 1, 2025 |
|---|---|---|
| Bodily injury, per person | $30,000 | $50,000 |
| Bodily injury, per accident | $60,000 | $100,000 |
| Property damage | $25,000 | $50,000 |
Bodily injury and property damage liability pay the people you hurt and what you hit. They never pay for your injuries or your car. The liability limits page explains how to set limits above the floor.
UM and UIM are part of every policy
G.S. 20-279.21 makes uninsured motorist and underinsured motorist coverage part of every policy on a car registered or principally garaged in North Carolina. The statute has no rejection form for either. Its only choice is the limit: UM and UIM start at the highest bodily injury liability limit on the policy, up to $1 million, and you may buy more or less, but not below 50/100. Your UIM limit must equal your UM limit.
UM property damage
UM also pays for property damage, at your property damage liability limit up to $1 million, and you pay the first $100 of each claim.
UIM on top of liability
A driver is underinsured when the liability limits that apply are less than your total damages. Your UIM pays without a credit for that driver's liability payment; only workers' compensation can reduce it.
The UIM change matters most at modest limits. Whether a driver is underinsured now depends on your total damages, not on comparing two sets of policy limits. And the NC Department of Insurance says the UIM amount cannot be reduced by setoffs or credits against any coverage, including liability coverage, except workers' compensation as the statute provides.
Stacking and hit-and-run claims
- Within one policy, no stacking. The limit for one car cannot be added to the limit for another car on the same policy.
- Across policies, stacking is allowed. If more than one policy applies, the highest UM or UIM limit from each policy is added together. This applies to nonfleet private passenger policies.
- Hit-and-run. For a collision with a vehicle whose owner or driver cannot be identified, the crash must be reported within 24 hours, or as soon as practicable, to a police officer or the Commissioner of Motor Vehicles, and the insurer must get notice within a reasonable time.
- Lawsuits. Before you sue an uninsured driver, the statute requires 60 days' notice to your insurer.
The rules on stacking are explained in more detail on how stacking works.
Medical payments and optional coverages
North Carolina has no personal injury protection requirement, and the statute's list of required coverages does not include medical payments. MedPay, collision and comprehensive are optional, although a lender or lease company will require collision and comprehensive on a financed car.
Where to check and complain
- Read your declarations page. Insurers must state the required UM and UIM coverage there at issue and at renewal, in type no smaller than 12 point.
- Compare your UM and UIM limits with your liability limits, and ask your insurer about any lower limits you selected.
- Contact the North Carolina Department of Insurance at 855-408-1212 if an insurer will not explain a coverage or a claim decision.
Questions drivers ask
What are North Carolina's minimum car insurance limits?
50/100/50 for policies issued or renewed on or after July 1, 2025: $50,000 per person, $100,000 per accident and $50,000 for property damage.
Can I reject UM or UIM coverage in North Carolina?
No. Both are required on every policy. You can choose limits other than your liability limits, but not below the 50/100 minimum.
Does North Carolina UIM pay on top of the other driver's insurance?
Yes, under the July 1, 2025 rule. The UIM amount is not reduced by the at-fault driver's liability payment; only workers' compensation can reduce it.
Can I stack UM/UIM coverage in North Carolina?
Not within one policy. Across separate nonfleet private passenger policies, the highest limit from each policy is added together.
Drawn from
- NC Department of Insurance — Changes to the rating of automobile insurance policies, effective July 1, 2025
- NC Department of Insurance — Commissioner Causey reminds drivers of auto insurance policy changes (July 1, 2025)
- N.C. Gen. Stat. §20-279.21 (liability limits: (b)(2); UM: (b)(3); UIM: (b)(4); notice: (m))
Facts on this page were checked against these sources on November 15, 2026. The 50/100/50 minimums and the required UIM coverage apply to policies issued or renewed on or after July 1, 2025.
Have this coverage priced
CoverOath doesn't sell insurance. Answer five questions and CoverOath passes your request to licensed insurance agents and insurers, who can quote the coverage; you decide whether to buy anything.
- 1 The coverage you want priced.
- 2 Where an agent can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with a quote. Nothing is bought until you agree.
CoverOath is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Adjacent layers
-
Core coverage
Underinsured motorist coverage (UIM)
Pays your injuries above the at-fault driver's limit. Added-on UIM stacks on their payment; offset UIM subtracts it.
-
Core coverage
Uninsured motorist property damage (UMPD)
Pays to fix your car when an identified uninsured driver is at fault. California caps it at $3,500.
-
Fine print
Stacking UM/UIM coverage
Whether UM limits on several cars add up. Pennsylvania and Florida stack by default; California bans it.