UM required
South Carolina coverage menu: liability and uninsured motorist required, underinsured offered
South Carolina makes every policy carry two coverages and makes insurers offer a third. It also keeps the deductible off safety glass. Here is what each line pays.
By CoverOath Editorial Team Updated 6 min read
The promise, in short
South Carolina requires 25/50/25 liability and uninsured motorist coverage at the same 25/50/25 amounts, including $25,000 for damage to your own property. Insurers must also offer underinsured motorist coverage and higher UM limits, which you may decline. There is no PIP mandate; medical payments coverage is optional. Physical damage deductibles do not apply to automobile safety glass. The Department of Insurance's Office of Consumer Services answers questions at 1-800-768-3467.
- Minimum liability
- 25/50/25
- PIP
- No PIP; MedPay optional
- UM/UIM
- UM required; UIM offered
South Carolina coverage menu
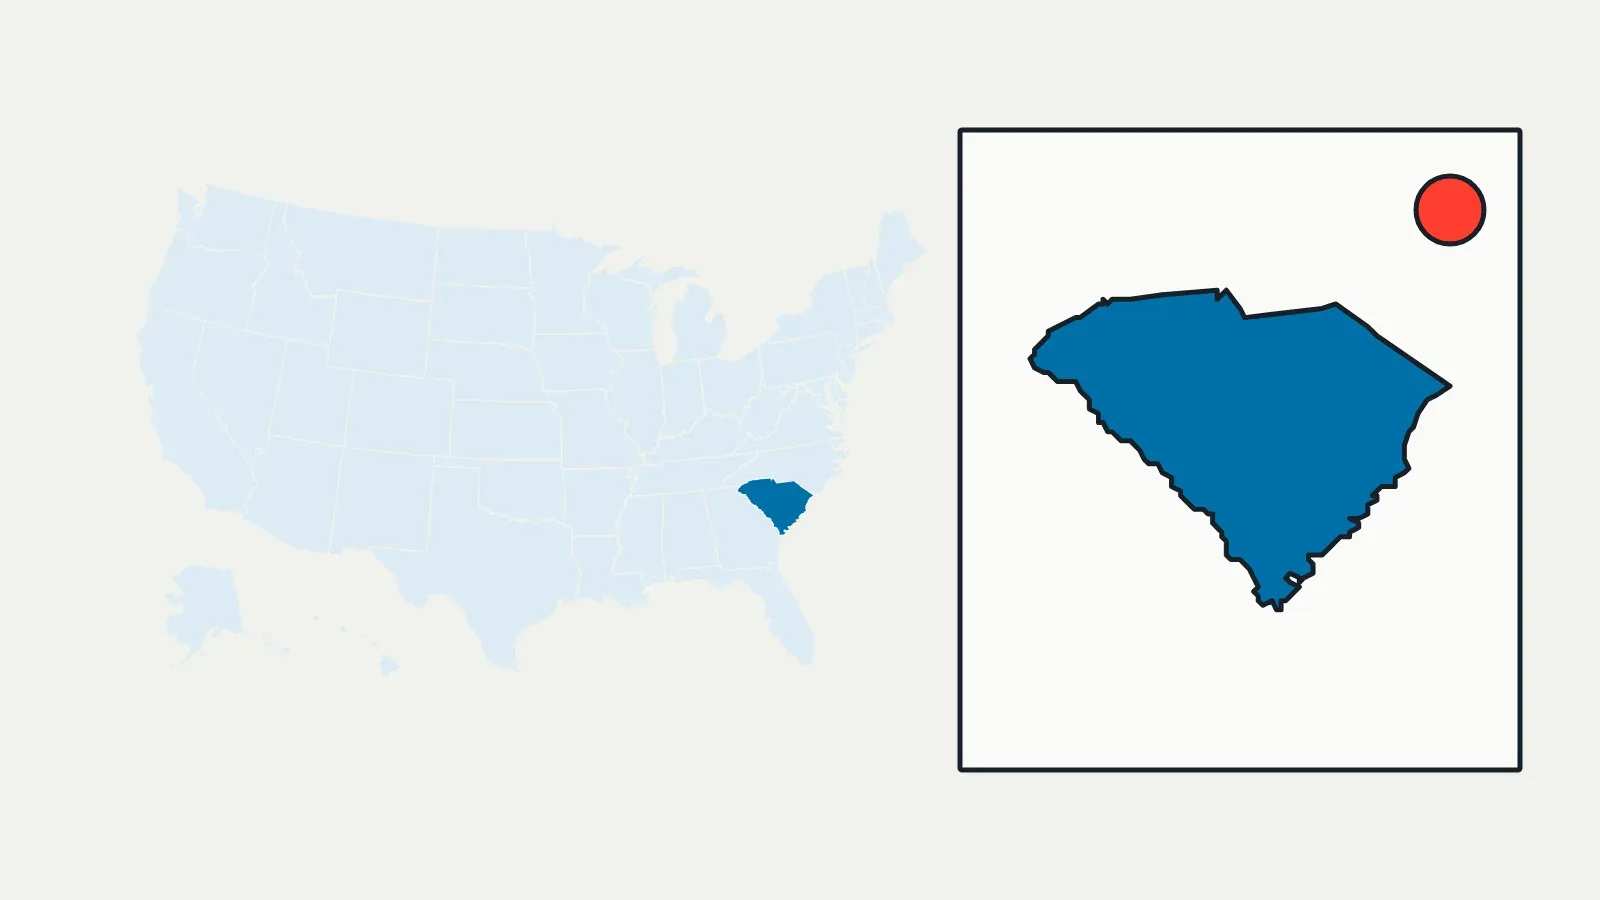
What a South Carolina policy must carry
The South Carolina Department of Insurance says you must buy liability and uninsured motorist coverage to drive legally. Section 38-77-140 sets the liability floor, and §38-77-150 makes every policy include UM within limits no lower than those amounts.
| Coverage | Minimum | Whom it pays |
|---|---|---|
| Bodily injury liability | $25,000 per person / $50,000 per accident | People you injure |
| Property damage liability | $25,000 per accident | Property you damage |
| Uninsured motorist, bodily injury | $25,000 per person / $50,000 per accident | You and others insured, hurt by an uninsured driver |
| Uninsured motorist, property damage | $25,000 | Your property, damaged by an uninsured driver |
The statute allows the UM property damage part to exclude the first $200 of a loss, so expect a $200 deductible on that line. See uninsured motorist property damage for how it differs from collision.
Underinsured motorist coverage and higher UM limits
Section 38-77-160 requires insurers to offer two things on top of the mandatory UM: additional uninsured motorist coverage up to your liability limits, and underinsured motorist coverage. Both are your choice. The Department of Insurance states that underinsured coverage is not mandatory.
Stacking and hit-and-run rules
South Carolina's statute limits how the optional layers combine. If you carry excess UM or UIM on several vehicles, §38-77-160 says you are protected only to the extent of the coverage on the vehicle involved in the accident. If none of your vehicles is involved, coverage is available only up to the coverage on any one of them. How stacking works explains the terms. If you insure several cars, ask your insurer how this rule and your policy wording apply to your household.
When the at-fault driver is unknown, §38-77-170 lets you recover under UM only if:
- the accident was reported to an appropriate police authority within a reasonable time;
- the injury or damage came from physical contact with the unknown vehicle, or the accident was witnessed by someone other than the owner or driver of the insured car who signs an affidavit, or there is a recording of the accident; and
- you were not negligent in failing to identify the other vehicle.
No PIP, optional MedPay
Section 38-77-144 states that no personal injury protection coverage is mandated under South Carolina's auto insurance laws. The Department of Insurance lists medical payments coverage as optional. Without either, your crash injuries are paid by the at-fault driver's liability, your UM or UIM, or your health insurance.
Zero deductible on safety glass
Section 38-77-280(B) says automobile physical damage deductibles do not apply to automobile safety glass. The Department of Insurance explains that the deductible for glass coverage is waived, and that you need comprehensive coverage on the vehicle for the insurer to replace the windshield. Without comprehensive, there is no glass coverage to waive a deductible on. The full glass coverage page explains how glass options work in other states.
Optional coverages South Carolinians add
- Collision for your own car regardless of fault; a lender or lease company will require it.
- Comprehensive, which is also what brings the safety glass rule into play.
- Add-ons such as rental reimbursement, roadside assistance and gap coverage on a financed car.
The mandatory UM line pays for damage to your car only when an uninsured driver causes it, and only after the $200 the statute allows insurers to exclude. Collision pays whoever caused the crash, after your collision deductible. The two answer different questions.
Where to check and complain
- Read your declarations page for liability, UM bodily injury and property damage, any UIM, and whether comprehensive is listed.
- Ask the insurer how UIM and any added UM limits apply to each car if you insure more than one.
- Call the Department of Insurance Office of Consumer Services at 1-800-768-3467 (803-737-6180) if an insurer will not explain a coverage or a claim decision.
Questions drivers ask
Is uninsured motorist coverage required in South Carolina?
Yes. Every policy must include UM at 25/50/25, including $25,000 for property damage. The property damage part may carry a $200 deductible.
Is underinsured motorist coverage required in South Carolina?
No. Insurers must offer it, and you may decline it. It is the coverage that pays when the at-fault driver has insurance but not enough.
Do I pay a deductible for a windshield in South Carolina?
No deductible applies to automobile safety glass, but you need comprehensive coverage on the vehicle for the insurer to replace the windshield.
Does South Carolina require PIP?
No. State law says no PIP coverage is mandated. Medical payments coverage is optional.
Drawn from
- South Carolina Department of Insurance — Automobile insurance
- South Carolina Department of Insurance — Auto insurance FAQs
- S.C. Code Title 38, Chapter 77 (§38-77-140 limits, §38-77-144 PIP, §38-77-150 UM, §38-77-160 UIM, §38-77-170 hit-and-run, §38-77-280 glass)
Facts on this page were checked against these sources on November 15, 2026. The safety glass rule is in §38-77-280(B) and applies only where the car has physical damage coverage.
Have this coverage priced
CoverOath doesn't sell insurance. Answer five questions and CoverOath passes your request to licensed insurance agents and insurers, who can quote the coverage; you decide whether to buy anything.
- 1 The coverage you want priced.
- 2 Where an agent can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with a quote. Nothing is bought until you agree.
CoverOath is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Adjacent layers
-
Core coverage
Underinsured motorist coverage (UIM)
Pays your injuries above the at-fault driver's limit. Added-on UIM stacks on their payment; offset UIM subtracts it.
-
Core coverage
Uninsured motorist property damage (UMPD)
Pays to fix your car when an identified uninsured driver is at fault. California caps it at $3,500.
-
Add-on
Full glass coverage
Removes or lowers the comprehensive deductible on glass. Florida, Kentucky and South Carolina set it at $0 by law.