Offer, reject in writing
California coverage menu: liability required, UM/UIM on the policy unless you sign a waiver
California requires liability and puts uninsured motorist coverage, which also covers underinsured drivers, on every policy unless you sign it away. Here is what each line pays and what the law leaves out.
By CoverOath Editorial Team Updated 6 min read
The promise, in short
California requires 30/60/15 liability: $30,000 per injured person, $60,000 per crash and $15,000 for property damage, raised from 15/30/5 on January 1, 2025 by SB 1107, which also schedules 50/100/25 for January 1, 2035. Uninsured motorist coverage, which in California also answers for underinsured drivers, must be on the policy unless you and the insurer agree in writing to delete or reduce it. Uninsured motorist property damage has a $3,500 limit. There is no PIP; medical payments coverage is optional. The California Department of Insurance hotline is 1-800-927-4357.
- Minimum liability
- 30/60/15
- PIP and MedPay
- No PIP; MedPay optional
- UM/UIM
- Included unless waived
California coverage menu
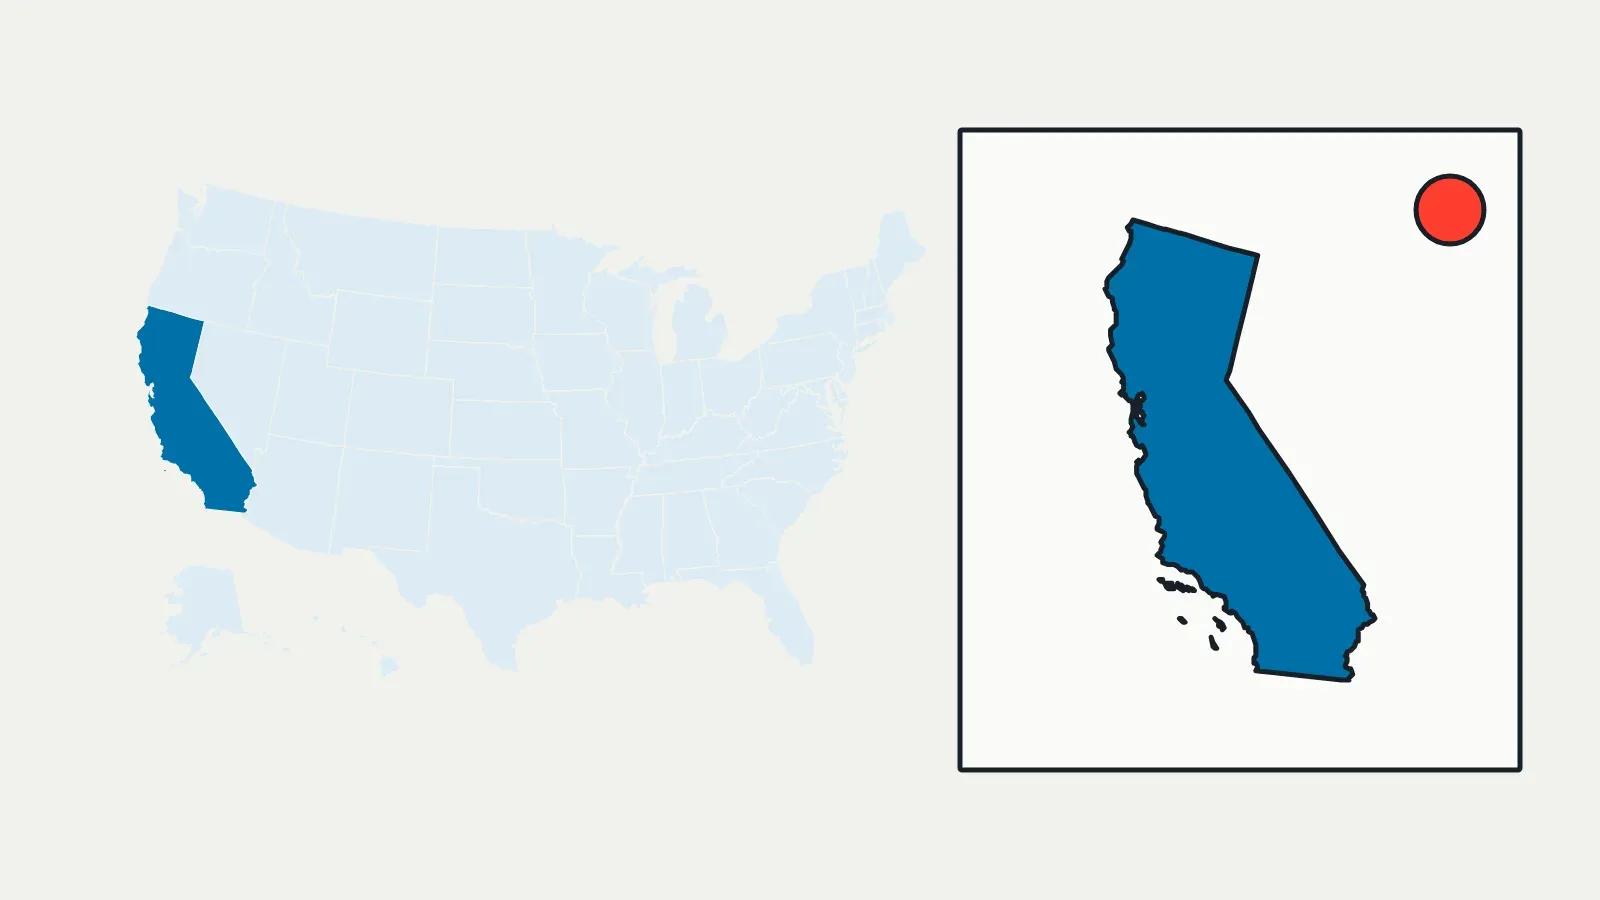
What a California policy must carry
The California Department of Insurance (CDI) lists these as the minimum limits for a standard auto policy, in its auto insurance guide revised February 5, 2025. The DMV cites Insurance Code §11580.1b for the same figures. Liability pays the people you injure and the property you damage; it pays nothing for your own injuries or car.
| Coverage | Minimum | What it pays |
|---|---|---|
| Bodily injury, per person | $30,000 | One injured person's claim |
| Bodily injury, per accident | $60,000 | Everyone injured in one crash |
| Property damage, per accident | $15,000 | Other people's cars and property |
A $15,000 property damage limit can run out on a single newer car, and what a court awards above your limits is owed by you. The liability limits guide explains how people choose higher limits.
UM and UIM stay on unless you sign
Insurance Code §11580.2 requires every auto liability policy to include uninsured motorist coverage for bodily injury unless the insurer and a named insured agree in writing to delete it or reduce it. The statute prescribes the wording of that agreement. CDI puts it plainly: the insurer must offer the coverage, and if you choose not to buy it, you must sign a form called a waiver.
Underinsured is part of UM
California treats a vehicle insured for less than your UM limits as underinsured. The most UIM pays is your limit minus what the at-fault driver's side has paid you. See UIM.
Hit-and-run needs contact
When the owner and driver are unknown, the injury must arise from physical contact between that vehicle and you or your car. The statute also sets reporting and sworn-statement steps.
Property damage is separate
UM bodily injury does not pay for property damage. Uninsured motorist property damage is its own coverage; CDI gives its limit as $3,500.
The written agreement can do two things: delete UM bodily injury entirely, or reduce it to a lower limit. Once signed, it relieves the insurer of liability for the coverage it removes. Because UIM sits inside UM in California, a waiver of UM also takes away the protection against a driver whose limits are too low. If you keep UM, its limit is also the yardstick for UIM: a driver counts as underinsured only when their limits are below yours.
No stacking in California
Section 11580.2 does not let you add UM limits together. When two or more vehicles or two or more policies could apply, the limits are not combined; damages are capped at the higher applicable limit and the coverages share the payment. A household with two cars at $30,000 UM each has $30,000 for one person, not $60,000. See how stacking works.
No PIP; MedPay is optional
California is a fault state with no personal injury protection requirement. Medical payments coverage is optional; CDI says it pays for immediate medical care no matter who is at fault, and the lowest limit you can buy is $1,000 for each person injured.
Optional coverages Californians add
- Collision and comprehensive for your own car; a lender or lease company will require both. See collision coverage.
- Rental reimbursement while a covered repair is done. See rental reimbursement.
- Rideshare coverage if you drive for an app. A personal policy can exclude the time the app is on. See the rideshare endorsement.
Where to check and complain
- Read your declarations page for your liability limits and whether UM bodily injury and UM property damage are listed.
- Ask the insurer for a copy of any signed UM waiver if the coverage is missing or lower than you expected.
- Call the CDI Consumer Assistance Hotline at 1-800-927-4357 (TTY 1-800-482-4833) if an insurer will not explain a coverage or claim decision.
Questions drivers ask
Is uninsured motorist coverage required in California?
It must be included in every policy unless you and the insurer agree in writing to delete or reduce it. If you did not sign a waiver, it is on your policy.
What is the minimum car insurance in California?
30/60/15 liability since January 1, 2025: $30,000 per person and $60,000 per accident for injuries, and $15,000 for property damage. Under SB 1107 the minimum rises to 50/100/25 on January 1, 2035.
Can I stack UM coverage in California?
No. Insurance Code §11580.2 bars adding UM limits across vehicles or policies. See stacking.
How much does uninsured motorist property damage pay in California?
The California Department of Insurance gives the limit as $3,500.
Drawn from
- California Department of Insurance — Automobile insurance guide (Form 101, rev. Feb. 5, 2025)
- California DMV — Insurance requirements (Insurance Code §11580.1b)
- California Insurance Code §11580.2, uninsured and underinsured motorist coverage (Justia, 2025 edition)
- SB 1107 (Chapter 717, Statutes of 2022), Vehicle Code §16056 limits for 2025 and 2035 (chaptered text, LegiScan)
Facts on this page were checked against these sources on November 15, 2026. CDI's guide and the DMV both list 30/60/15 as the current minimum, in force since January 1, 2025 under SB 1107.
Have this coverage priced
CoverOath doesn't sell insurance. Answer five questions and CoverOath passes your request to licensed insurance agents and insurers, who can quote the coverage; you decide whether to buy anything.
- 1 The coverage you want priced.
- 2 Where an agent can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with a quote. Nothing is bought until you agree.
CoverOath is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Adjacent layers
-
Core coverage
Uninsured motorist coverage (UM)
Pays your injuries when an uninsured or hit-and-run driver is at fault. Required in about 20 jurisdictions.
-
Core coverage
Uninsured motorist property damage (UMPD)
Pays to fix your car when an identified uninsured driver is at fault. California caps it at $3,500.
-
Fine print
Stacking UM/UIM coverage
Whether UM limits on several cars add up. Pennsylvania and Florida stack by default; California bans it.