UM + UIM required
Nebraska coverage menu: liability, UM and UIM on every policy
Nebraska makes both uninsured and underinsured motorist coverage part of every auto liability policy. Here is what the required lines pay, how to raise them, and why two policies do not add up.
By CoverOath Editorial Team Updated 5 min read
The promise, in short
Nebraska requires 25/50/25 liability and, on every policy, uninsured and underinsured motorist coverage of $25,000 per person and $50,000 per crash. At the named insured's written request the insurer must provide higher UM/UIM limits, though it does not have to go above $100,000 per person. When several policies apply, you collect no more than the highest limit of any one of them. There is no PIP requirement. The Nebraska Department of Insurance runs a complaint hotline at 877-564-7323 (in-state).
- Minimum liability
- 25/50/25
- PIP
- Not required
- UM/UIM
- Both required at 25/50
Nebraska coverage menu
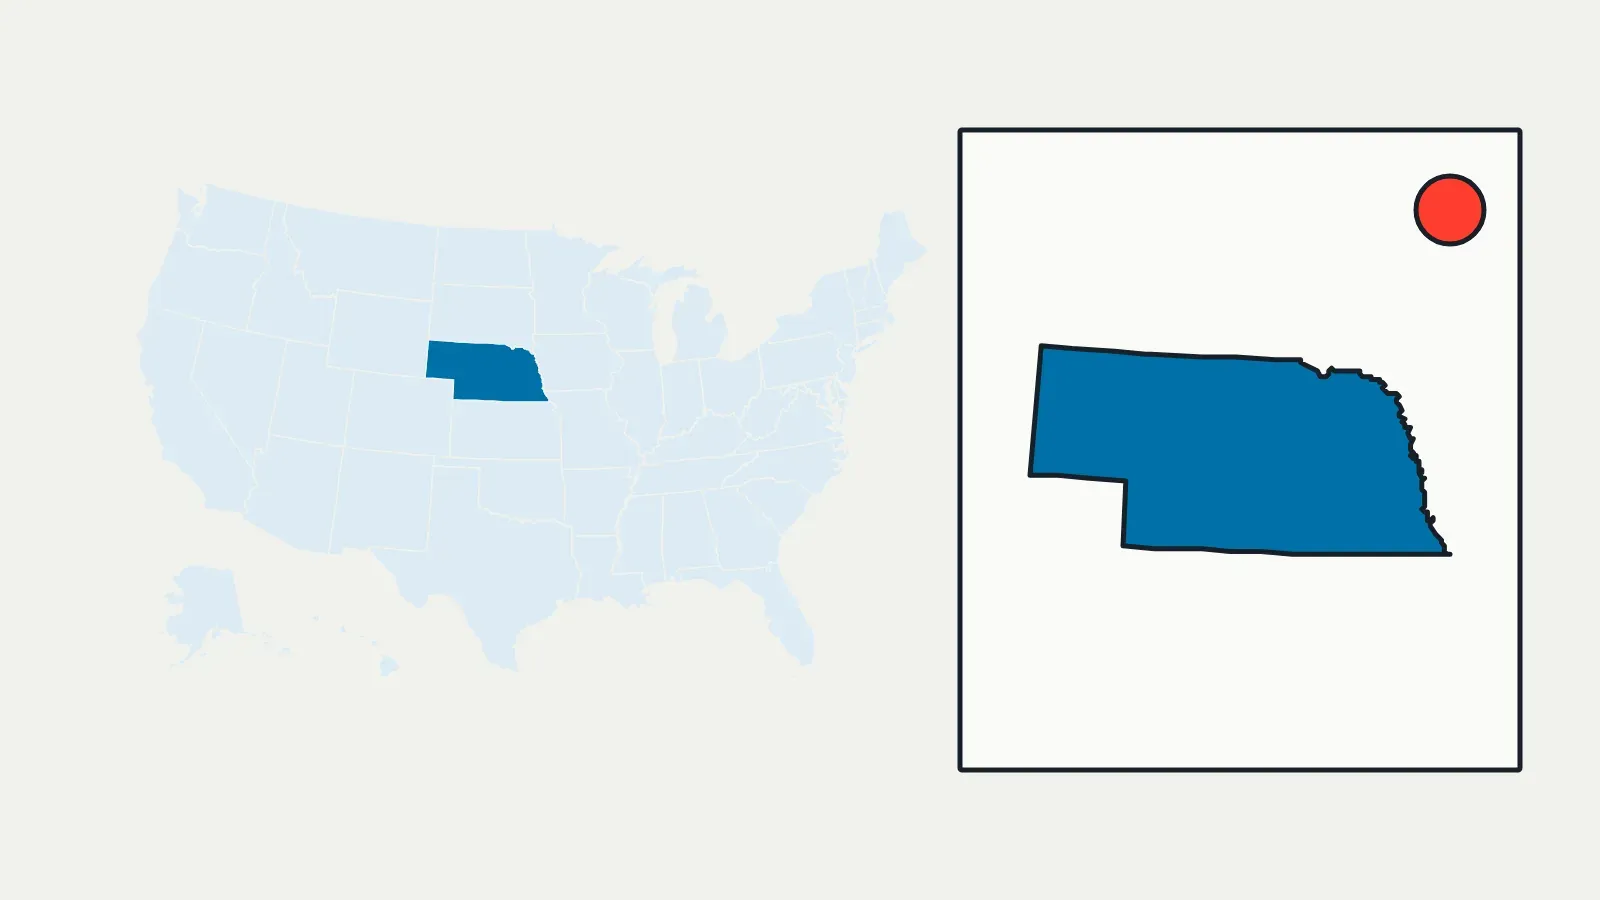
What a Nebraska policy must carry
Nebraska defines the minimum auto liability policy in Neb. Rev. Stat. §60-310 and requires uninsured and underinsured motorist coverage in §44-6408. Together they make three required lines: liability, UM and UIM.
| Coverage | Minimum | What it pays |
|---|---|---|
| Bodily injury liability | $25,000 / $50,000 | People you injure, per person / per crash |
| Property damage liability | $25,000 | Other people's cars and property |
| Uninsured motorist | $25,000 / $50,000 | Your injuries caused by an uninsured driver |
| Underinsured motorist | $25,000 / $50,000 | Your injuries above the at-fault driver's limits |
The liability limits are the floor, and anything above them is yours to pay. The liability limits page explains how people choose higher ones.
Nebraska's required UM and UIM lines are the two coverages on the list that pay you rather than other people. UM pays when the driver who hurt you has no liability insurance. UIM pays when that driver has insurance but too little for your injuries, up to your UIM limit.
UM and UIM are part of every policy
Under §44-6408, no auto liability policy may be delivered, issued or renewed for a vehicle principally garaged in Nebraska unless it includes uninsured and underinsured motorist coverage at 25/50. The statute has no procedure for rejecting the minimum.
Raising the limits
At the named insured's written request, the insurer must provide higher UM/UIM limits, up to $100,000 per person if you ask for that much.
Injuries only
The required coverage pays bodily injury, sickness, disease and death. The statute does not require property damage coverage for your car.
Some vehicles do not count
Neb. Rev. Stat. §44-6407 lists vehicles that are not treated as uninsured or underinsured; court notes under it cover regular-use and government-owned vehicles.
Because the required coverage does not touch your car, damage from an uninsured driver goes through your own collision coverage, if you carry it, after its deductible.
No stacking in Nebraska
Neb. Rev. Stat. §44-6411 bars adding limits together. When you have UM or UIM coverage under more than one policy, the most you can recover is the highest limit of any one policy. The statute also sets the order in which policies pay:
- First: the policy covering the vehicle you were in at the time of the crash. Its UM/UIM coverage is primary when you were in a car you do not own.
- After that: other coverage available to you applies only once the primary coverage is used up, and never above the highest single limit.
A case noted under the statute on the Legislature's website, Weston v. Continental Western Ins. Co., sums up the rule: stacking of uninsured motorist coverages is prohibited. How stacking works explains the terms.
Optional coverages Nebraskans add
- Medical payments, for medical bills for you and your passengers whoever caused the crash. Nebraska has no PIP requirement.
- Collision and comprehensive for your own car. A lender or lease company will require both for as long as the loan or lease runs.
- Add-ons such as rental reimbursement and gap coverage on a financed car.
Each optional line has its own limit, and collision and comprehensive each carry a deductible. None of them raises what your policy pays to people you injure; only the liability limit does that. A buyer who wants more room for a large lawsuit raises the liability limit or adds an umbrella policy on top.
Where to check and complain
- Read your declarations page for your liability limits and your UM and UIM limits.
- Ask the insurer in writing if you want UM/UIM limits higher than 25/50.
- Contact the Nebraska Department of Insurance at 877-564-7323 (in-state complaint hotline) or 402-471-2201, or file a complaint online.
Questions drivers ask
Is uninsured motorist coverage required in Nebraska?
Yes. Every auto liability policy must include uninsured and underinsured motorist coverage of at least $25,000 per person and $50,000 per crash.
Can I buy more UM/UIM than 25/50 in Nebraska?
Yes. The insurer must provide higher limits at the named insured's written request, though it is not required to go above $100,000 per person.
Can I stack UM/UIM coverage in Nebraska?
No. With coverage under more than one policy, you can recover no more than the highest limit of any one policy.
Drawn from
- Neb. Rev. Stat. §44-6408 (required UM/UIM coverage and limits)
- Neb. Rev. Stat. §44-6411 (limits across policies; priority)
- Neb. Rev. Stat. §44-6407 (vehicles excluded from UM/UIM)
- Neb. Rev. Stat. §60-310 (automobile liability policy minimums)
- Nebraska Department of Insurance — Consumer contacts and complaints
Facts on this page were checked against these sources on November 15, 2026. UM/UIM rules were read from the Uninsured and Underinsured Motorist Insurance Coverage Act, Neb. Rev. Stat. §§44-6401 and following.
Have this coverage priced
CoverOath doesn't sell insurance. Answer five questions and CoverOath passes your request to licensed insurance agents and insurers, who can quote the coverage; you decide whether to buy anything.
- 1 The coverage you want priced.
- 2 Where an agent can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with a quote. Nothing is bought until you agree.
CoverOath is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Adjacent layers
-
Core coverage
Uninsured motorist coverage (UM)
Pays your injuries when an uninsured or hit-and-run driver is at fault. Required in about 20 jurisdictions.
-
Core coverage
Underinsured motorist coverage (UIM)
Pays your injuries above the at-fault driver's limit. Added-on UIM stacks on their payment; offset UIM subtracts it.
-
Fine print
Stacking UM/UIM coverage
Whether UM limits on several cars add up. Pennsylvania and Florida stack by default; California bans it.